 The Meme
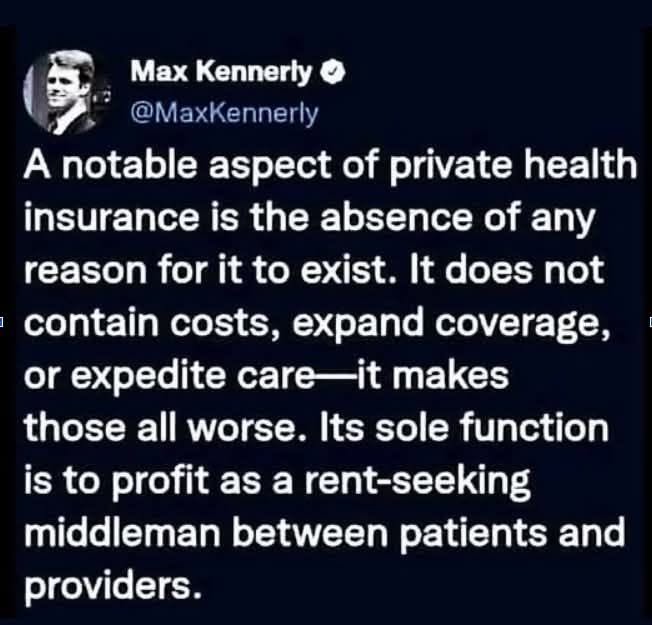
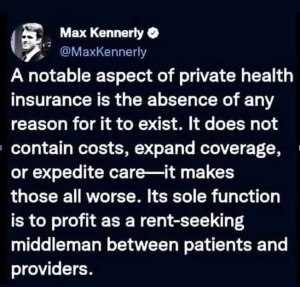
This post is my reaction to a meme going around slamming medical insurance. Promoters of this meme compare medical insurance to ticket scalpers, and the meme states that medical insurance has no reason to exist. The text of the meme is:
A notable aspect of private health insurance is the absence of any reason for it to exist. It does not contain costs, expand coverage, or expedite care—it makes those all worse. Its sole function is to profit as a rent-seeking middleman between patients and providers.
I take issue with almost every part of that text.
Personal Context
I worked for a medical insurance carrier for 35 years, as a programmer, analyst, and project manager. I spent most of my decades working in the Claims Payment and Provider (aka doctor/hospital) side of things, though I had forays into the Membership side as well. (Those three areas are seen as the pillars of the medical insurance model.)
The company I worked for began as a non-profit, meaning it had no shareholders. It was started in 1917, when timber workers in the Puget Sound region decided to pay into a common fund to pay for medical costs when one of them was injured and unable to work. When I left, the company was still a non-profit; we were not unique in this, but we were definitely in the minority. Our membership was about 6 million souls across a six-state region.
During my time, for each dollar that came in, about 10% went to running the business (salaries, rents, utilities, improvements), a small portion went into legally required reserves (to pay for claims when amounts exceeded revenue, to keep premium fluctuation to a minimum), and most (80–85%) went to paying the claims for our members.
That said, I will be one of the first to support the idea that the medical insurance industry needs work. The proliferation of for-profit medical insurance companies in the ’80s and ’90s was (in my opinion) a betrayal of the basic tenets of the industry, i.e., to provide affordable medical care to a community by distributing the burden from individuals to the group, and not to maximize profits. It should be noted that also during that period, hospitals began switching from non-profit to for-profit models. Before 1970, almost all insurers and hospitals were non-profit. Now, about 70% of insurers and 24% of hospitals are for-profit.
Group Insurance Expands Coverage
The idea that medical insurance has no reason to exist (as stated in the meme) is by far the most ludicrous part of the argument. Medical insurance, like home insurance and vehicle insurance, is designed to limit the financial hit one might take should tragedy or accident befall us. Homeowners who don’t insure their house would likely be wiped out if fire took their home. States actually require us to carry vehicle insurance, because aside from damage to our own vehicle, we could be at fault and cause damage and/or harm to other cars and people. Insurance takes that financial risk and distributes it out; we hope we don’t need it, but if we do, it’s there to help us manage the costs and help those we might have hurt.
I can only imagine that a person who states that medical insurance has no reason to exist never got a bill for an uninsured emergency appendectomy or a few rounds of chemo. Those timber workers, back in 1917, knew that medical care was expensive, and that by sharing the load, each paying a smaller amount, regularly, they could create a fund (aka “reserves”) to cover costs should one of their group be injured. Costs are even higher, today, especially as shareholders demand dividends in addition to providing care.
More to the point, many medical insurers (like the one I worked for) are the processors of claims that come from the ACA/Obamacare. The government isn’t processing those claims. Insurers are. People who never had insurance before the ACA are able to go to the doctor and have their claims paid because the medical insurance industry is processing that claim.
Without group-based insurance, many people would not be able to have medical care. Injuries and diseases would go untreated. Private health insurance, therefore, on its own and as a partner with the government’s ACA, absolutely expands coverage, as a monthly premium can more easily be factored into a household budget than can a massive bill for a hospital stay.
Negotiated Rates Contain Costs
A major way medical insurance provides value is by negotiating rates of reimbursement with hospitals and doctors. Insurers negotiate with networks of doctors and hospitals to bring down costs; the doctors and hospitals get access to the insurer’s large pool of patients, and the patients are charged a lower amount than if they’d walked in off the street without insurance.
Example: Last year I had a heart attack. EMTs (bless ’em) took me to the ER, and I spent a couple of nights in the hospital while I was stabilized and had a stent put into one of my arteries. The hospital charged me $66,415 for the stay and care I received. However, my insurer had negotiated a lower rate with that hospital, and the reduced (or “allowed”) amount was only $15,278. That’s a 75% reduction in the original charge. Then the insurer paid most of that reduced amount. I still owed a chunk, about a grand, but without insurance I would have been on the hook for over $66k.
Someone please explain to me how that scenario is not an example of containing costs.
Expertise to Expedite Care
The charge that medical insurance does nothing to expedite care, well, that’s a crapshoot, as performance on this metric can be all over the place. The sheer complexity of the industry—and oh, it is complex—is a major source of frustration to members. So while many insurers really suck at this part of the job, others put a lot of effort into assisting their members when things get tangled up.
Whether it’s a competent cadre of customer service folks who willingly help you intercede with a hospital’s billing and administration sectors, or it’s a managed-care agent who helps coordinate all of the various aspects of a complicated course of treatment, things can go a lot easier with an expert to guide you, and many medical insurers provide these services. Sadly, it’s not a given, but most insurers regularly poll their members, and there are industry organizations (like the NCQA) the sole purpose of which is to track the clinical quality, patient experience, and accreditation of plans.
The Irony of the Meme
The upshot of the meme that got me started on all this is that we should do away with private health insurance—a thing that has no reason to exist—and replace it with Medicare for All.
Medicare for All is . . . health insurance.
Medicare is health insurance, it’s just funded by the government. But those Medicare claims? They’re processed by private health insurers.
Wrap-up
Personally, I’m all for Medicare for All. I’d like to see all the for-profit medical insurance industry completely overhauled, especially where mega-conglomerates control the entire ecosystem of the industry, running hospitals, clinics, and then processing the claims for them. At it’s heart, though, and as originally intended, non-profit insurers and hospitals were built to provide affordable care, dedicated to the patient while managing costs and making care accessible to everyone.
But to state that something that has existed for a hundred years has no reason to exist and provides no benefit is to be willfully blind to reality and the ramifications of what its absence would actually mean.
So, yeah, medical insurance is messed up, needs a lot of improvement, shouldn’t have shareholders who pervert its purpose, and should be universally available. I’d just rather have a reasoned discussion of the topic than distill everyone’s rage and frustration down to a few lines in a meme.
k